
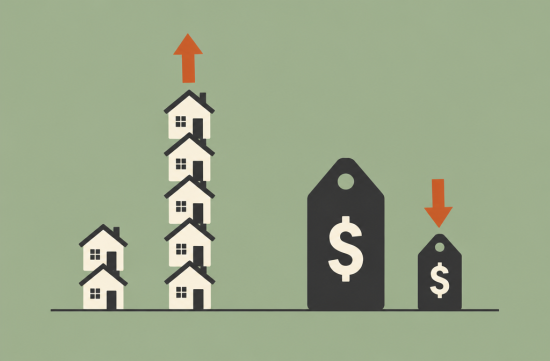
In a nutshell, the New Haven market in October can be summarized like this: while sellers are lowering their asking prices, actual transaction prices are still holding steady.
However, the benchmarks for each number vary. As of the time this article was compiled, the listings and asking prices available until October are current, while the transaction statistics by city are from September.
First, here are the October numbers. According to data from Realtor.com published by FRED for the New Haven-Milford metropolitan area, there are 888 active listings in October. This is a 15.6% increase from 768 listings in October of last year.
The median asking price from the same data is $425,000, down 7.55% from $459,700 in October of last year.
The time homes are staying on the market has also increased from 38 days to 43 days.
However, this is a metropolitan area statistic that includes Milford and reflects asking prices, not transaction prices. It would be misleading to interpret this as a more than 7% drop in home prices in New Haven city.
Now, regarding actual transactions by city. According to the September report from SmartMLS, the median sale price for single-family homes in New Haven is $395,000, which is a 5.5% increase from $374,500 in September of last year.
However, there were only 23 transactions that month. The cumulative median price from January to September is $365,400, which is actually a 1.2% decrease. I place more weight on this cumulative figure than on just one month's data.
Still, the single-family home market remains strong. In September, homes sold for 102.4% of the listing price, and it took 30 days to sell. Inventory is down to 76 homes, a decrease of 18.3%, which is about 3.4 months' worth of supply.
The condo market, however, shows a different trend. The median price in September was $255,000, which is a 47% increase from $173,500 last year, but with only 13 transactions, this figure is somewhat misleading. The cumulative median price is $256,000, reflecting a more realistic 1.8% increase.
Condo inventory has increased to 65 units, up 14%, and represents 4.5 months' worth of supply. It took 50 days to sell, and they sold for 98.2% of the listing price.
Single-family homes still favor sellers, while condos present a market where buyers can negotiate.
According to SmartMLS weekly data, as of the week ending October 24, the inventory in New Haven County is 1,440 single-family homes, down 2.2%, while condos are at 566, up 20.9%.
Why are asking prices dropping while actual transaction prices are holding steady? The statistics vary widely, making it difficult to draw definitive conclusions. My interpretation is that overpriced listings are reducing their prices, while well-maintained homes continue to attract competition, leading to polarization.
According to Freddie Mac's announcement on November 5, the 30-year fixed mortgage rate is at 7.18%, and the 15-year fixed is at 6.57%. This is a significant increase from 6.22% for the 30-year fixed a year ago.
If you apply a 20% down payment on the September median price of $395,000 with a 30-year fixed rate of 7.18%, my calculations show that the principal and interest alone would be $2,141 per month. Property taxes and insurance are additional.
Rental rates vary significantly by source, so they should be viewed separately. The median rent in the November report from Apartment List is $1,813, which is up 0.7% from the previous month and 1.5% from a year ago.
According to the same report, Connecticut overall saw a 0.5% increase, while the national average rose by 0.1%, indicating that New Haven is slightly ahead.
The updated Zumper page from early November lists the average rent at $2,050, which is nearly the same as last year. A two-bedroom unit is listed at $2,000. Since the methods of aggregation differ, do not mix these two figures; instead, observe each trend separately.
Neighborhood differences are even more pronounced. According to Zumper, downtown averages $2,695, while East Rock is at $2,300. Westville and Hill are both at $2,050, Newhallville at $1,700, and Edgewood at $1,625.
Even within the same city, there can be significant variations. East Rock, close to Yale, benefits from demand from students and researchers, while Westville has a more tranquil residential feel. The average prices by neighborhood can fluctuate based on the composition of listings, so consider them as reference points only.
On the local issue front, news about supply is the most significant. In April of this year, the city's Planning Commission approved Phase 1 of Union Square, located across from Union Station. This phase includes three buildings with over 500 units, with a total plan of 2,500 units, and completion of Phase 1 is expected by 2030.
The former Winchester factory site on Shelton Avenue in Newhallville is also undergoing redevelopment. According to WFSB reports, over 240 units will be built on the adjacent site, all aimed at households earning 60% or less of the area median income.
The same report states that the city has set a goal of 10,000 units over the next 10 years, with 30% of those being affordable, and that 5,800 units are currently in the pipeline. Long-term investors should take this into account.
On the demand side, a variable is healthcare employment. Marcus and Millichap's Q2 2026 report noted that hiring in the healthcare sector has slowed due to workforce reductions at Yale New Haven Health. There are no additional layoffs planned for this year.
If you are a primary residence buyer, I wouldn't expect significant discounts on asking prices for single-family homes. For condos, it may be worth making offers below the listing price.
If you are a tenant, consider bringing the rental statistics mentioned above into your discussions during lease renewals. If the proposed increase seems excessive, you can also contact the city's Fair Rent Commission.
If you are an investor, with rental increases likely capped at around 1% while interest rates are in the 7% range, it's wise to approach cash flow conservatively. Property taxes vary by home, so check the city Assessor's data directly.
I would look at the next SmartMLS report for the number of transactions in October and condo inventory. It will help determine whether the decline in asking prices translates to actual transactions.
 skybreezefox1950



 uplifted |

 Dr. Kelso |

 silents |
 Choco Choco Star |
 gentle |
 Dream Mong |
 Lee Sang Don |
 Jenny's Mom blog |

 Hagen |
 nova nova |
 figtop |
 Yahoo LALA |
 Korea News Economic News |
 calvor |
 timistic |
 victoria jung |
 The Long Shot |
 Univ Student |
 Bald Eagle Brothers |
 Tora Tora |
 pandaworld |
 lumix88 |
 choi family |
 Lansinger |
 Giant Squid and Sweet Potato Soup |
 InJung Gu |
 cake money |
 swiftlane |