
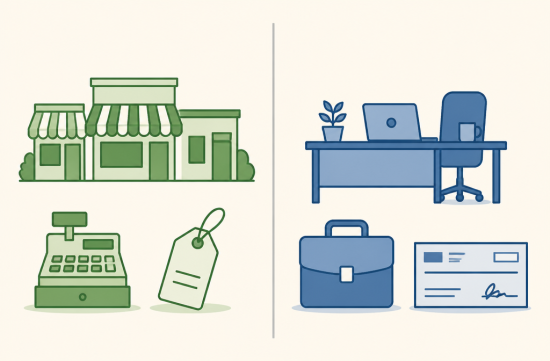
When observing the generation of parents who leave early in the morning and close their shops late at night, and the generation of children who start work at nine and finish at six, a natural question arises: who ends up wealthier?
This topic recently came up in a gathering with friends, and everyone spoke with confidence based on their own family experiences. Curious about the actual statistics, I decided to look into it.
According to the Federal Reserve's Consumer Finance Survey, the median net worth of self-employed households was $380,000 as of 2019. In contrast, wage-earning households had a median net worth of only $90,000.
At first glance, the self-employed seem to be significantly ahead, with more than four times the wealth, which surprised me initially.
However, before fully trusting this statistic, there are some points to consider. The average net worth can rise to $2.7 million, but this is skewed by the wealth of a few individuals, creating a significant gap from the median value.
There is also a tendency for individuals with some existing wealth to start businesses, suggesting that it is not so much that business creates wealth, but rather that those who are already financially comfortable tend to venture into business.
Gallup's survey shows that this disparity becomes even more pronounced. The median personal income for business owners with employees was $110,000, while self-employed individuals operating alone earned only $24,000. For reference, regular wage earners without a business made $62,000.
This means that even within self-employment, the income gap can widen significantly depending on whether the business has employees or is run solo. Many of the laundries or small markets commonly seen in Korean neighborhoods tend to fall into the latter category.
The higher income for business owners with employees likely stems from their ability to create a structure that allows the business to operate without the owner being present. In contrast, a solo-operated store sees immediate revenue drops if the owner is absent for even a day, making it difficult to increase their own value until the business scales up.
Recent trends in the Korean community indicate a decline in the proportion of self-employed individuals. One economic survey found that the percentage of self-employed individuals dropped from 24.4% in 2020 to 19.6% in 2023, and this year it has fallen to 17.6%.
While some first-generation business owners are retiring, it seems that the increasing tendency of the younger generation to choose traditional employment plays a significant role. Children who grew up seeing their parents open shops even during holidays may understandably not want to follow that path.
This trend is not unique to the Korean community. Looking at the broader picture in the U.S., there is not a noticeable increase in the proportion of self-employed individuals, suggesting that this is part of a larger generational shift.
The risks associated with self-employment cannot be overlooked. According to the Bureau of Labor Statistics, about 20% of new businesses close within a year, and nearly half shut down within five years.
When discussing net worth, one must also consider time. Gallup's survey indicates that 49% of self-employed individuals work over 44 hours a week, and 26% work more than 60 hours. When factoring in the hours worked, the hourly wage can tell a very different story.
On the other hand, employees have a fixed monthly salary, and companies often provide health insurance and retirement matching, which may offer more favorable conditions for steadily building wealth.
Self-employed individuals can benefit from tax deductions for business expenses, but they must fully cover their own health insurance, which can be a significant burden. Additionally, even if the business itself is an asset, it does not provide liquid cash unless sold.
Self-employed individuals also need to manage their own retirement accounts, but in the hustle to meet sales targets, I have often seen them postpone this aspect. In contrast, employees tend to accumulate savings automatically due to deductions from their paychecks.
Nowadays, many in the younger generation are increasing their wealth through stock or real estate investments while still employed, making the boundaries between the two generations less distinct than before.
Ultimately, whether one becomes wealthier seems to depend more on how much they grow their business or how consistently they save and invest their salary, rather than simply being self-employed or an employee.
Personally, I believe it is not advisable to urge the younger generation to run a business like their parents did. Times have changed, and the initial capital and labor costs are incomparable to the past.
However, it is also difficult to claim that traditional employment is the only answer, as it ultimately comes down to how each individual manages their risks, making it hard to definitively say which generation is better off.
 EastBakery

 moname |
 mapsina |
 Mr. Largo |
 Victory 1988 |
 Infinite Style |
 neapolis |

 topsi |
 postcard |
 cheesecake07 |
 My Miami Stories |
 windylotus |
 Mia Flori |
 velaro29 |
 velaro |
 foxtrot83 |
 mapleline |
 US Legal Consultation on Trials |
 UNI Lover |
 Karina's Blog |
 California Dreamer |
 Choco Mint Creator |
 Chili Boy Club |
 NE Hodori Preik |
 Giant Squid and Sweet Potato Soup |
 torvik |
 charger |