
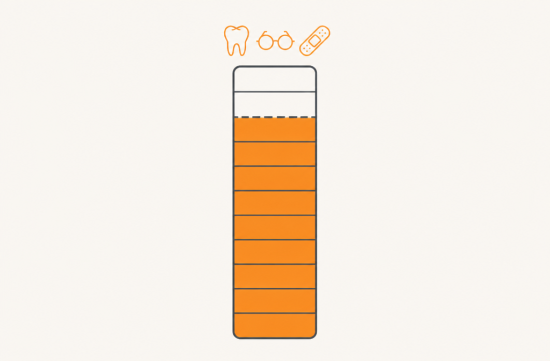
Every December, it becomes particularly difficult to schedule appointments for dental or eye care.
When you call, the representative often says, "Everyone is trying to get in around this time," and at first, I thought it was just because everyone is busy at year-end.
However, there was a different reason. It's all about health insurance deductibles.
A deductible is the amount you must pay out of pocket before your insurance benefits kick in.
As of 2026, the minimum deductible for high-deductible plans is set at $1,700 for individuals and $3,400 for families.
You start filling this amount from January, and once you reach it, the insurance company begins to cover a significant portion of your medical expenses.
There's also another level to consider: the out-of-pocket maximum.
For 2026, the out-of-pocket maximum for high-deductible health plans is $8,500 for individuals and $17,000 for families.
If you're using a marketplace plan instead of employer insurance, this maximum is slightly higher at $10,600 for individuals and $21,200 for families.
Once you reach this maximum, it means that all medical expenses for the remainder of the year will essentially be covered by insurance.
So, if a family had a major injury in the summer that required surgery, they likely have already met their family deductible and maximum.
In that case, the remaining months can be an opportunity to get overdue check-ups or procedures without worrying about medical bills.
Common items that tend to pile up during this time include dental crowns or implants, glasses or contact lens prescriptions, physical therapy, and postponed colonoscopies.
It's also important to note that every January 1st, this amount resets to zero.
However, some companies have plan years that start in July or October instead of January, so it's essential to check when your plan resets.
I've heard stories of people who scheduled major procedures at the beginning of a new plan year without realizing they would have to start filling their deductible from scratch.
Therefore, many people believe that waiting for the new year after having filled their deductible is a loss.
When you add in the discussion about FSA, the reasons become even clearer.
An FSA is a pre-tax account set aside for medical expenses, but as of 2026, the limit for rolling over to the next year is only $680.
Depending on the company, they may offer a grace period instead of a rollover, but that period is usually not very long, typically until March 15 of the following year.
Ultimately, any money exceeding the rollover limit simply disappears after midnight on December 31.
On the other hand, HSAs are different. The family contribution limit for 2026 is $8,750, and this money does not disappear with the new year; it continues to accumulate.
So, families with money in an FSA are more likely to visit hospitals, optical shops, and dental offices diligently at year-end.
Considering that family insurance premiums are not insignificant, this trend makes more sense.
As of 2025, the average annual premium for employer-sponsored family insurance was $26,993, with employees contributing $6,850 of that amount.
Seeing that amount deducted from my paycheck each month makes me feel a bit heavy-hearted.
When I think about how much I've already paid, it seems wasteful not to utilize the benefits after filling the deductible.
To find out how much I've already paid, checking the insurance app or EOB is much more accurate than relying on hospital bills.
I personally make it a habit to check the family insurance deductible and out-of-pocket maximum amounts at the beginning of each year.
This way, I can gauge how much has been filled by mid-year and reduce the stress of scrambling to make appointments at year-end.
If year-end hospital appointments are particularly tight, it's safe to assume that everyone is doing similar calculations.
 Dancing Fox



 holy cheese |
 Softy |
 Michigan Enthusiast |
 Anna Life |
 JESIKYEOALBA BLOG |
 zenvior |
 tarvion |
 velaro |
 velaro29 |
 foxtrot83 |
 moname |
 mapleline |
 US Legal Consultation on Trials |
 UNI Lover |
 Karina's Blog |
 California Dreamer |
 Choco Mint Creator |
 Chili Boy Club |
 NE Hodori Preik |
 Giant Squid and Sweet Potato Soup |
 torvik |
 charger |
 Pleasant K |
 Rolling Joy Life |
 lidus |
 French Macarons |