
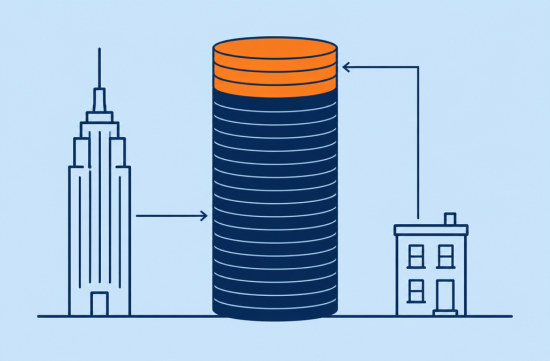
Every November, friends commuting to Manhattan via PATH always ask me, "Am I paying taxes twice?" It's just a river crossing, but I was initially overwhelmed by how complicated the tax paperwork is.
Let me share the conclusion first. You file twice, but you don't pay taxes on the same income twice.
The reason for the double filing is that there is no reciprocity agreement between New Jersey and New York. Residents of New Jersey working in Pennsylvania only pay their income tax to New Jersey thanks to this agreement, but New York is a different story.
New York taxes income earned within the state. New Jersey taxes all income of its residents, regardless of where it was earned.
The document that resolves this overlap is Schedule NJ-COJ. It's a credit form that allows you to deduct taxes paid to other states from your New Jersey tax, and it's submitted along with NJ-1040.
The process starts with New York. You must complete the non-resident tax return IT-203 to determine your New York tax amount, which is then used to calculate your New Jersey tax.
The credit is determined by the lesser of the two amounts: the actual tax paid to New York and the tax you would have paid to New Jersey if that income had been earned there. This is based on the New Jersey Division of Taxation guide GIT-3W, January 2026 edition.
The calculation for the latter amount is straightforward. You divide the income taxed by both states by the New Jersey taxable income and multiply that by the New Jersey tax.
Let's look at a hypothetical scenario for easier calculation. Suppose your New Jersey taxable income is $100,000, with $80,000 of that taxed by New York, and your New Jersey tax is $4,000. The limit would then be $3,200.
If you actually paid $4,500 in taxes to New York, your credit would be $3,200. You would only owe New Jersey the remaining $800, and you wouldn't get back the extra $1,300 paid to New York.
What surprised me most was the meaning of "actual tax paid." It's not just the withholding amount shown on your W-2.
GIT-3W explains that this amount is the tax before subtracting credits and withholdings. If you enter the withholding amount as is in the year you receive a refund from New York, the numbers will be incorrect.
The income section can also be tricky. New York uses worldwide income to determine tax rates, but the guide specifies not to use that section for credit calculations. You should refer to the New York State Amount section on IT-203.
Not all income earned in New York is taxable income. Due to deductions, the actual taxable amount may be lower, and the New Jersey Division of Taxation states that it cannot pinpoint a specific line on IT-203. Even if the tax program fills it out, double-check this section.
If you own a home that receives a property tax deduction, you also need to complete Worksheet I from the NJ-1040 guide. Write the local code on line 44 of NJ-1040, and starting from the 2025 tax year, include it on line 1 of NJ-COJ as well.
Since it's November, check your pay stubs. The New York State Department of Taxation states that if you are not a resident of New York City, you are not subject to NYC income tax. If the NYC item is still being withheld, you should immediately ask your HR department.
There are also many cases where the New Jersey item is empty. If a New York company only withholds New York taxes, the difference that isn't covered by credits will show up during filing.
There are several reasons for the difference. Bank interest or dividends are usually not considered New York taxable income, so they don't factor into credit calculations. The New Jersey single tax rate, based on the 2025 rate schedule, is 6.37% for income over $75,000, so depending on your income structure, there may still be a New Jersey tax liability.
If you think you'll owe more than $400 to New Jersey after accounting for withholdings and credits, you need to make estimated payments using NJ-1040-ES. The deadline for the last quarter of this year is January 15, 2027. The tax department warns that failing to do so may result in interest charges during filing.
Remote workers face an additional layer of complexity. If the company's office is in New York, days worked from home in New Jersey are generally counted as New York workdays.
This is known as the convenience of the employer rule. There are exceptions if the company has established the home as a formal office, but simply having permission to work from home is not enough.
This rule has survived into this year. On July 2, 2026, the New York State Appellate Court ruled that the rule is constitutional in the case of Professor Zelinski, who worked from home in Connecticut. The professor has stated that he intends to take the case to the Supreme Court.
Honestly, it feels a bit unfair that New York takes taxes for days worked from home. However, since each state has different positions, it seems more like a legislative issue than just waiting for a ruling.
It's worth considering the days you worked outside of New York for company purposes. If New York recognizes the income allocation based on workdays, the taxable income will decrease, which will also reduce the income used for New Jersey credit calculations.
This is the extent of my November check-in. Look for the New York State item on your pay stub and check if there's no NYC item. Also, see if last year's New Jersey balance exceeded $400.
Mark remote and business trip days on your calendar in advance. Keep copies of IT-203 and W-2 in one place. While you don't need to submit copies during filing, the New Jersey Division of Taxation advises keeping them in case of an audit.
If only one spouse works in New York or if there's mixed income from other states or freelance work, the calculations will change. In such cases, it's best to look for examples of GIT-3W and confirm with a tax professional for peace of mind.
If I were you, even if using tax software, I would personally verify the income and tax amount sections of NJ-COJ.
Tax discussions are always a headache, but once you understand them, there's no need to be overly worried. Feel free to share this with a colleague sitting next to you on your commute. The more people know about this, the less confusion there will be for everyone.
 BulgogiParty

 kodak |
 Valley Hong |
 Casa Mia |
 CA Real Estate |
 Eldorado 88 |
 Uptown |
 Living in New Jersey blog |
 Jersey City |
 Starlight Night Cloud |
 canyon |
 juniper |
 novaline |
 sunny side |
 kimchi warrior |
 nero kim |
 refresh |
 rainyday |
 springw |
 American History This and That |
 goldenleaf |
 mistily |
 selviro |
 strongman |
 Waiting for Godot |
 Sunny Mom |
 Blondee |
 El Dorado |
 passive |
 gardener 007 |