
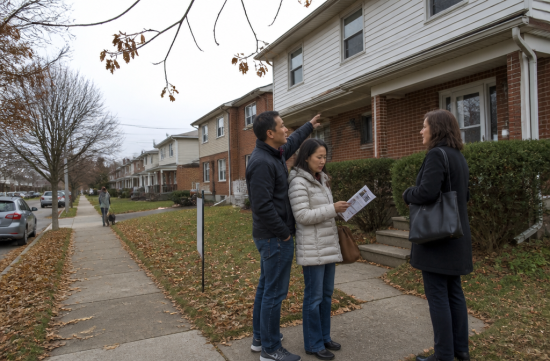
For those considering whether to buy a home or extend their rental in Columbus, the first numbers to look at are two: the median rent of $1,294 and a 30-year fixed mortgage rate of 7.18%.
While rent remains stable, interest rates are 0.96 percentage points higher than a year ago. The mood in the market this fall can largely be explained by these two figures.
For clarity, the rental data comes from the Apartment List and Zumper's October data, while the sales data is from the Columbus Realtors' September report released on October 13.
As of the time I checked, October sales statistics have not yet been released, so I am using September figures.
The median rent in Columbus according to the November report from Apartment List is $1,294. This is a decrease of 0.5% from last month and an increase of 0.4% from a year ago.
By bedroom type, the one-bedroom averages $1,117 and the two-bedroom averages $1,338. This is 6.5% lower than the national median of $1,384, making it relatively more affordable.
The October figures from Zumper are slightly different, showing one-bedroom rents at $1,155 and two-bedrooms at $1,350, which are a bit higher, and both have decreased by 4% compared to last year.
With one source showing a slight increase and the other showing a decrease, it can be confusing. This discrepancy likely arises from differences in data collection methods and sample sizes, but both sources agree that rents are not rising.
If I received a lease renewal notice, I would first check the asking prices of nearby complexes. In such a quiet market, there's no reason to accept a rent increase without question.
Sales should be viewed by region and within city boundaries. The median price for the entire Columbus area in September was $334,250, up 2.8%, while the median inside the city was $287,553, up 2.7%.
The rate of increase is nearly the same, but the price difference is $46,697. If you move to a popular school district, the gap widens even more, with the median in the Olentangy school district at $589,500.
While prices have risen, transactions have cooled. The number of closed sales in the region for September was 2,550, down 5.7%, and the number of contracts was 2,448, down 12.7%.
Conversely, listings have increased to 6,530, up 12.3%. The months of inventory have also risen from 2.3 months to 2.6 months.
The time it takes to sell a home has lengthened from 30 days to 33 days. Sellers received 98.8% of the final asking price, but compared to the initial asking price, it was 96.3%.
The difference between these two percentages is quite revealing. Homes that were initially priced high tend to sell only after a price reduction.
However, it's too early to call this a buyer's market. While 2.6 months of inventory is an improvement from the past, it's not at a level that can be considered ample.
When you factor in interest rates, the picture changes. The average 30-year fixed rate from Freddie Mac as of November 5 is 7.18%, compared to 6.22% a year ago.
If you buy a median-priced home inside the city with a 20% down payment, your principal and interest payment would be $1,558 per month. This is a figure I calculated myself, excluding property taxes and insurance.
If you calculate the same home with last year's interest rate, it would be $1,412. This means you are paying an additional $146 per month due to interest rates rather than home prices, which is frankly a bit frustrating.
When compared to the two-bedroom rent of $1,338, it is already $220 higher before taxes and insurance are included. The down payment of $57,511 is separate.
Therefore, if I anticipate moving within a few years, I would choose to rent. If I have already decided on a school district where I plan to stay long-term, it would be better to negotiate the asking price now that inventory has increased.
The first issue is property taxes. This year, Franklin County is undergoing a three-year value update, and according to Axios, the average increase for residential properties is 9%.
The review session at the auditor's office ended on September 5, and the final values are expected to be released in December. The auditor's office explains that taxes do not necessarily increase by the same rate as property values.
However, if there are disagreements, you can formally appeal to the Board of Revision. According to county forms, the deadline is March 31 of the following year, so be sure to check the schedule on the auditor's website.
The second issue is the property tax reform bill HB 186 signed last December. For owner-occupied homes, the existing 2.5% rollback and 10% credit will be combined, and this credit will increase to 15.38% by 2029.
For rental properties, it's the opposite. The non-business credit will decrease by one-fourth each year starting in the 2026 tax year, disappearing by 2029, with the 2026 amount due in 2027.
The actual impact will vary depending on the levy structure by school district. Even the same house in the same neighborhood will see credits increase if you live in it, but disappear if you rent it out.
If you are an investor, you will need to revisit the property tax item in your yield calculations. If rents remain stable but taxes increase, the perceived yield can diminish faster than expected.
The third issue is zoning. The city's draft for Phase 2 of the zoning plan aims to expand mixed-use areas and revise standards for industrial, warehouse, and office campus zones, with public feedback ending on October 24.
The city is positioned to increase housing supply, but I have not been able to confirm the city council's voting schedule. If you are interested in development sites, it's best to check the zoning map on the city's website directly.
In summary, renters have room for negotiation, while buyers have more options at the cost of higher interest rates. Homeowners should prepare for the final values in December and the changes from HB 186.
Taxes and loans vary based on personal circumstances, so be sure to consult with a professional before entering any numbers. Personally, I would choose to take my time comparing listings rather than rushing in this market.
 ThreeChicken




 Dr. Kelso |

 silents |
 Choco Choco Star |
 gentle |
 neapolis |
 steadyo |
 U.S. Weather Bureau News |
 strongman |
 Ohio Ohayoung Hello |
 constant |
 American History This and That |
 goldenleaf |
 mistily |
 selviro |
 Waiting for Godot |
 Sunny Mom |
 Blondee |
 El Dorado |
 passive |
 gardener 007 |
 zanero |
 Arlington house |
 Cali M Law Group |
 Delicious Food Finder |
 ultron78 |
 pet dog |
 networky |
 Sandiego Auntie |
 Macon Boy |