
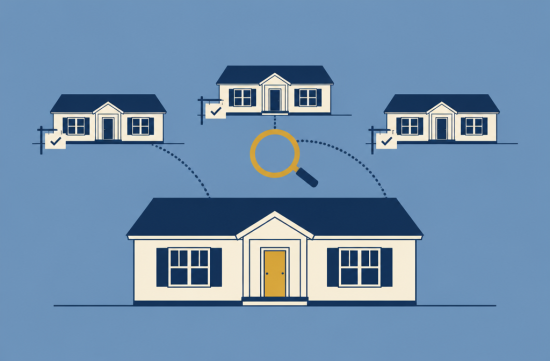
As November approaches, more people are checking the county auditor's website for their home's new assessed value. This year, Hamilton County is particularly busy due to the triennial update for the 2026 tax year.
According to the auditor's website, this update involves a statistical desktop review of over 350,000 parcels. Staff do not visit homes directly.
The finalized values will be released around the end of the year after state approval, and taxes will be due in 2027. If the numbers come in higher than expected, it's time to start preparing.
Let's take an example of a home. Suppose it's a three-bedroom ranch house from the 1960s, and the assessed value has increased more than anticipated. The homeowner feels unfairly treated, claiming their home is assessed higher than the neighbor's.
However, this logic won't hold up. The auditor's Board of Revision clearly states that the difference in assessed values with unsold neighboring homes is not credible evidence.
The claim that taxes are too high is similarly ineffective. The board does not consider the amount of tax as a basis for review. The only factor they examine is market value.
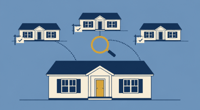
Thus, successful appellants start by gathering comparable properties. These must be homes that have actually sold, and ideally, they should be normal independent transactions.
It's safer to exclude transactions that may not reflect market value, such as sales between family members, foreclosures, or distressed sales. There's no need to include data that the opposing party could easily challenge.
Next, here are the criteria for similarity. The notice advises using recent sales of homes that are similar in size, shape, and age within the same area.
I would look for homes in the same school district, preferably within the same neighborhood block. The size difference should be minimal, and I would compare ranch homes with ranch homes. It's also good to match the completion status of basements and the size of garages.
The timing is important too. In Ohio, January 1st is the tax assessment date, so for the 2026 tax year, the market around January 1, 2026, will be the reference point.
Therefore, properties sold around that date will be the most persuasive. If the market has cooled in recent months, selectively choosing those transactions could weaken your case.
If you've identified about three comparable properties, honestly note the differences between them and your home. If that house has a renovated kitchen and yours does not, you shouldn't hide that difference.
Include documentation that shows the condition of your home. The auditor cites dated photos and certified repair estimates as evidence. If there are issues with the roof or foundation, this can carry significant weight.
The strongest evidence is an appraisal report. The notice identifies an appraisal dated as of the assessment date as the best evidence.
On the other hand, older appraisals or those for refinancing have limited value. Many people submit documents from a refinance a few years ago, but they may not be as effective as expected.
If you recently purchased your home, the process is even easier. The purchase agreement and closing documents serve as strong evidence on their own.
Remember the application timeline. The Board of Revision accepts appeals from January 1 to March 31 each year, and mail postmarked by March 31 is accepted.
The form for residential properties is DTE 1. Email submissions are not accepted, so you must submit via mail or the specified method.
One more thing: Ohio law limits the ability to repeatedly appeal the same parcel within the same assessment cycle. There are exceptions for normal sales or damages, but it's best to submit a thorough appeal the first time.
Evidence should be submitted with the application. Additional materials must be submitted at least 10 days before the hearing, and anything submitted later may not be considered.
Showing a phone or laptop screen on the day of the hearing is also not allowed. You must prepare printed or scannable documents.
The hearing is typically brief, lasting about 15 minutes. It's short. It's better to present a single page of comparable properties and a few photos to convey the key points quickly.
If the board has sufficient evidence, they may accept the requested value without requiring your presence. If your presence is necessary, you will be notified at least 10 days in advance.
If you disagree with the outcome, you can appeal to the Ohio Board of Tax Appeals or the county civil court within 30 days from the date the decision notice is sent. Missing this deadline will result in dismissal.
It's also worth noting that since this is a desktop review, there may be errors in records such as the number of bedrooms or square footage.
If you encounter such simple errors, request corrections from the auditor's office before filing an appeal. If the records are corrected, that alone may adjust the assessed value.
Just because the assessed value increases doesn't mean taxes will rise by the same percentage. The auditor explains that tax rates and credits also play a role. So, there's no need to get overly excited just by seeing the numbers.
My conclusion is simple. Instead of feeling wronged, preparing three sold homes, photos, and, if possible, an appraisal dated as of the assessment date will lead to success. Since the specific conditions vary by home, I recommend checking directly with the auditor's office or the board's notice for guidance.
 RubyNote
 ForestWalker



 Choco Choco Star |

 gentle |

 neapolis |

 moo moo |
 ultron78 |
 peace |
 Real Estate Investment Korean American |

 ssome |
 skykong |
 Shining Our Own World |
 gardener 007 |
 golfmaster |
 Nanana Nanana Nanana |
 Who's watching? |
 endone |
 RockStar |
 Casa Mia |
 You Only Live Once |
 Hardworking CPA |
 Joyce 77 |
 Runner Kim |
 My Town My Way Blog |
 My Miami Stories |
 Entip |
 Tony Park |
 Jean Claude Bundang Blog |
 DJ DC BLOG |