
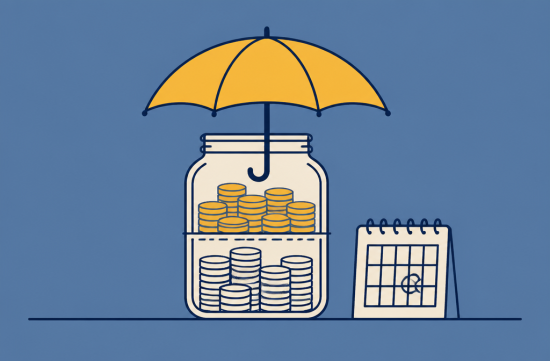
These days, when discussions about retirement preparation come up, there's always one question that arises: "Does New York tax pensions?"
To put it simply, not necessarily. If certain conditions are met, you can deduct up to $20,000 from your state income tax calculation from your pension and IRA withdrawals each year.
However, many people end up losing out because they only have a vague understanding of this system. So, I looked up the guidelines from the New York State Department of Taxation and Finance and summarized the key points.
The official name is Pension and Annuity Income Exclusion. It appears on line 29 of the resident income tax form IT-201.
The basic requirement is straightforward. If you were 59 and a half or older for the entire tax year, you can exclude up to $20,000 of qualified pension and annuity income from your federal adjusted gross income (AGI) from your New York AGI.
Qualified income includes private company pensions, 401(k) withdrawals, and traditional IRA distributions. However, remember that the $20,000 limit is a total cap, not per item.
For example, if you receive $15,000 from a company pension and withdraw $10,000 from an IRA, only $20,000 of the total $25,000 will be deducted, and the remaining $5,000 will be taxable.
What I found most interesting is the rule for the year you turn 59 and a half. If you turn 59 and a half during that year, only the amounts received after that date are eligible for the deduction.
This means that if you withdraw money from your IRA before your birthday when you turn 59 and a half, that amount will not qualify for the deduction. Even if you withdraw the same amount later in the year, the timing can change the outcome.
So, if you are turning 59 and a half that year, it's more efficient to postpone your withdrawal schedule until after that date. The federal early withdrawal penalty of 10% typically also lifts at age 59 and a half, so I recommend marking that date on your calendar.
If you are married, the calculations can be even more favorable. If both spouses have pension income, they can each claim a maximum deduction of $20,000, whether filing jointly or separately.
However, each spouse must have their own pension income. You cannot transfer unused limits from one spouse to the other.
So, if one spouse has all the funds in their IRA, they may only be able to utilize half of the limit. It's worth checking your account structure in advance.
Inherited pensions also need to be addressed. According to the tax department's guidelines, if the deceased was eligible for the deduction while alive, the beneficiary can use this deduction regardless of their age.
However, the total deduction for the deceased and all beneficiaries cannot exceed $20,000 per year. This means that if multiple siblings are sharing, they must divide this limit among themselves.
Public employee pensions are a completely different story. Pensions from New York State, local governments, and the federal government are fully exempt from tax, separate from the $20,000 deduction.
Moreover, there are no age requirements for this. Therefore, public employee pensions are fully excluded, while the $20,000 deduction applies separately to private IRAs or 401(k) withdrawals.
Social Security benefits are also not taxed by New York State. Even if they are partially included in federal income, they are deducted separately on the state return.
After summarizing this, I felt that New York State is not as harsh on retirees as one might think. Of course, when considering property taxes and living expenses, the situation changes.
When it comes to actually claiming this, the steps are as follows. First, confirm the exact date you turn 59 and a half.
Next, gather your pension income documents, such as the 1099-R, and separate them into public pensions, private pensions, and IRA withdrawals. Then, divide the amounts by each spouse's name.
Finally, check with your tax software or tax professional to ensure that the deduction is correctly entered on the appropriate line of IT-201. Sometimes, it may not be included automatically, so it's good to verify.
Considering New York State's income tax rates, a $20,000 deduction is not an insignificant amount. Since it recurs annually, the difference becomes even more pronounced over the entire retirement period.
If I were in your shoes, I would create a withdrawal plan starting in my late 50s. By determining when and how much to withdraw from each account, it becomes much easier to fully utilize this deduction each year.
Of course, federal taxes, Medicare premiums, and other income can vary greatly from person to person. Since the outcomes can differ based on individual circumstances, be sure to consult a tax professional before making any final decisions.
For more detailed criteria, visit the retirement guide page and IT-201 instructions on the New York State Department of Taxation and Finance website. It's not a bad idea to read the original documents yourself at least once.
I believe that preparing for retirement is ultimately a battle of information. If only a few people are aware of the deductions, those who plan ahead and know will win the game.
 SodaJoy

 oh my salami |
 saffronroute |
 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 Belgray Miscellany |

 Static |
 namico |
 Delicious Food Finder |
 Mia Flori |
 nova nova |
 healthy |
 leaves |
 sparkling |
 maryland park |
 persiste |
 conte |
 blueman |
 Going Once |
 Eldorado 88 |
 cherrydino |
 garlic bread |
 middlekick |
 Moscow Kim |
 nivex85 |
 quanta7 |
 Tomato Health Club blog |
 horse |
 Egg Steamed Pot |