
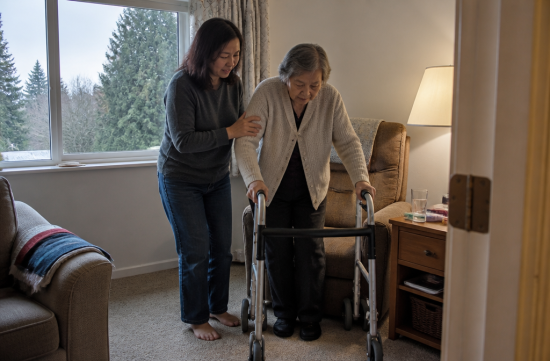
These days, there are many discussions about caring for parents. As a result, I often receive questions about whether the WA Cares benefits that started this summer can be used for our parents.
To put it simply, parents must have a record of paying insurance premiums directly in Washington state. The structure does not allow children to receive care benefits paid for by their own contributions.
Many people misunderstand this aspect more than you might think. I also initially thought it was a family benefit.
First, let's clarify the basics. WA Cares is a public long-term care insurance program operated by Washington state, which has been deducting 0.58% from workers' wages since July 2023.
To calculate, an annual salary of $50,000 results in a deduction of $290 per year, while $80,000 results in $464. If you've seen the WA Cares or LTSS item on your pay stub, that's it.
Actual benefits will start being paid out on July 1, 2026. The lifetime limit per person is $36,500 as of 2026, and it will be adjusted for inflation.
This is not a monthly cash benefit. It's set up like a bank balance, where a limit is established, and it is deducted each time approved services are used.
So, who can receive these benefits? To qualify for the insurance premium payment, one of three criteria must be met.
If you pay for more than 10 years, you gain permanent eligibility. If you have paid for 3 out of the last 6 years at the time of application, you gain temporary eligibility.
For the older generation, the third criterion is crucial. Those born before January 1, 1968, accumulate 10% of the total limit for each year they pay, which currently amounts to $3,650 per year.
However, to be recognized for a year, you must work at least 500 hours in that year. If you have been working part-time consistently, you may qualify.
This brings us to a realistic picture. If your parents retired before July 2023, they have no paid premiums, so they do not qualify.
On the other hand, if they are still running a business or working with premiums deducted from their pay, the situation changes. Benefits will be proportional to the years of contribution.
Self-employed individuals are generally not required to enroll and must choose to sign up separately. If your parents run a business, checking this aspect should be the first step.
There are also requirements for needing care. They must need help with three or more activities of daily living, such as bathing, eating, using the bathroom, moving, or managing medications, and this condition must be expected to last for more than 90 days.
There are over 40 services that can be used. These include in-home care, assistive devices, meal delivery, transportation, and household chores.
The most welcome aspect is the payment for family caregivers. If the beneficiary is approved, children or spouses can also become paid caregivers.
However, this does not mean receiving money personally; they must be affiliated with a home care agency registered with Consumer Direct Care Network Washington or WA Cares. Background checks, I-9 documentation, and a 5-hour online orientation and safety training are also required.
With CDWA, parents become the employers and set the schedule and tasks. The agency supervises and creates the care plan.
Which option is better depends on the family situation. If I were in this situation, I would consider CDWA if communication with my parents is smooth; otherwise, I would first look into the agency option.
Applications are made by creating an online account, submitting the care needs, and consulting with a representative. Results can be received via email, text, or mail, depending on the preferred method.
The initial response has been relatively quiet. The pilot program was first conducted for some residents of Lewis, Mason, Spokane, and Thurston counties.
As of June 22, just before the official launch, there were 113 applications, of which 44 were recognized as eligible.
I was a bit surprised by the numbers. It was estimated that between 25,000 and 35,000 people would qualify in the first year, so the start has been quite slow.
One more point to note is that beneficiaries who move to another state will be able to use the benefits starting July 1, 2030.
So, if your parents plan to move to a warmer state after retirement, you need to carefully consider the timing of the move and when to use the benefits.
It's difficult to cover all long-term care costs with $36,500. However, it is certainly not a small amount for several months of in-home care or meal delivery.
It's true that this system has been a topic of controversy in the political arena for a long time. However, if premiums have already been paid, I believe it's right to claim what can be received.
Results can vary significantly based on your parents' work history, birth year, and residence, so please make sure to check with the WA Cares consultation center or an expert according to your personal situation.
This weekend, I plan to look for my parents' pay stubs together. It's much more reassuring to know in advance rather than scrambling for documents when the time comes.
 RocketTiger

 oh my salami |
 saffronroute |
 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 French Macarons |

 Always Dreaming of Big Success |
 eclipse |
 US Snowboard Information Exchange |
 Mental Health Psychiatrist |
 element |
 Koreab Date |
 CA Real Estate |
 yolanda78 |
 Round and Round Children's Song Kingdom |
 Mia Flori |
 nova nova |
 healthy |
 leaves |
 sparkling |
 maryland park |
 persiste |
 conte |
 blueman |
 Going Once |
 Eldorado 88 |
 cherrydino |
 garlic bread |
 middlekick |