
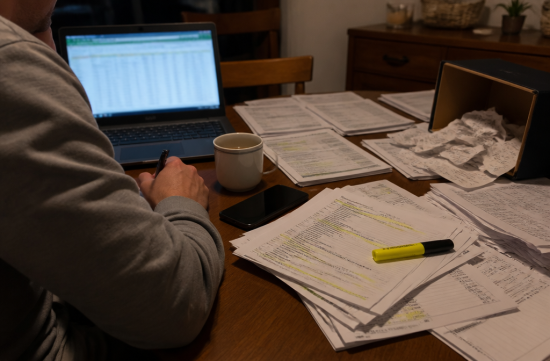
A friend of mine runs a small landscaping business and has been receiving business deposits into his personal account while using his business card for weekend grocery shopping for several years.
According to him, he thought, "It's all my money, so what's the problem?"
It wasn't until he received an IRS audit notice that he realized why it was a problem. The issue wasn't the taxes; it was the bank account.
The first thing an auditor does is not check receipts.
They take a complete look at the account deposit history.
The IRS internal guidelines (IRM 4.10.4) explicitly mention a method called bank deposit analysis.
This is a procedure for reconstructing income indirectly if reported income is not clearly explained in the books.
Looking at the request list in the audit notice gives you a sense of what's coming.
They request monthly statements for the entire year, images of canceled checks, credit card statements, and payment processor settlement details all at once.
The books come next. This means the auditor will consider the bank's records before the taxpayer's records.
The formula itself is simple. You take the total deposits, subtract transfers between accounts, cash that was withdrawn and then redeposited, and non-income deposits, and add the amounts paid in cash.
If the calculated amount is greater than the reported total income, that difference becomes a candidate for unreported income.
It's up to the taxpayer to prove that the difference is not income.
This means having to account for money sent by parents, borrowed from friends, or proceeds from selling a used car.
If he had only used a business account, he would have had to explain dozens of deposits, but because he mixed them, it becomes hundreds.
This multiplies the time and accounting costs significantly. The same goes for deductions.
IRS Publication 583 advises separating business accounts from personal checking accounts and depositing daily sales into the business account.
While this is a recommendation, in actual audits, it effectively acts as a baseline.
To claim a business expense, the purpose and amount must be connected in records, but if fuel, dining, and material costs are mixed in one account, that connection is broken.
Unsubstantiated deductions are simply disallowed.
If deductions are disallowed, additional taxes arise, and those additional taxes incur penalties.
The accuracy-related penalty under Section 6662 of the Internal Revenue Code is 20 percent of the underpayment amount.
For individuals, if the underreported amount exceeds the greater of 10 percent of the tax owed or $5,000, it is considered a substantial understatement.
Taking it a step further, the civil fraud penalty under Section 6663 comes into play, with a tax rate of 75 percent. I was honestly a bit shocked when I first saw that number.
However, this applies only if the IRS can prove willfulness with clear and convincing evidence. Simply mixing accounts does not automatically trigger this.
We also need to address the timing issue. The typical audit period is three years after filing.
However, that doesn't mean you can relax. Non-contractual disputes or tax liabilities follow a different track.
These days, it's even more complicated due to online payment service apps.
With the law signed on July 4, 2025, the threshold for issuing 1099-K forms has reverted to $20,000 annually and 200 transactions.
Don't be too relieved that the threshold has been raised.
Some states have lower thresholds, and platforms may issue forms voluntarily even below federal thresholds.
In summary, open separate checking accounts and cards for business use, and when adding or withdrawing personal money, label it as contributions or withdrawals in your records.
Also, create a separate business profile for payment apps and reconcile your account balance with your books at least once a month.
If it were me, I would open the accounts first on the day I start the business.
Spending an hour at the bank is much cheaper than having to explain years of deposit history line by line later.
 VelvetCore83
 TwinB
 QuitDiet


 Valley Hong |
 Casa Mia |
 CA Real Estate |
 Eldorado 88 |
 limestone |
 xylora |
 Texas Migration Story |
 Aura-Infused WACAM |
 Dalsabet dolstar |
 fantastic |
 nero kim |
 Alaska Salmon Buyer |
 solvix18 |
 California Information News |
 HAWAII Korean Church News |
 Raomi News |
 My Love DS |
 Hardworking CPA |
 People Moon |
 Carolina border |
 korian87 |
 dancing in the rain |
 bravo777 |
 yolo1990 |
 zentra95 |
 wishi |
 abox |
 Belgray Miscellany |