
Last week, I inadvertently overheard a conversation between two mothers in line at the Korean market. One said, "It's been a long time since we divorced, but I heard I can get something from his pension?" The other replied, "Oh, come on, you're divorced, what do you expect?" and laughed.
That comment stuck with me throughout my shopping. So, when I got home, I dug into some materials from the Social Security Administration (SSA) and a few articles.
To cut to the chase, the mother was right. It's a system that many people don't know about, and I was quite surprised. If the conditions are met, you can receive spousal benefits based on your ex-spouse's work record.
This is called ex-spouse benefits. It's a bit of a twist that just because you're divorced doesn't mean you're completely cut off from pension benefits.
The most important condition is the duration of the marriage. According to SSA guidelines, the marriage must have lasted at least 10 years, and the calculation is based on the date of divorce.
This means that 9 years and 11 months won't cut it. It's a bit scary to think that just one date on a divorce document can determine retirement benefits.
The second condition is age. The applicant must be at least 62 years old.
The third condition is that you must currently be unmarried. If you have remarried, you generally cannot receive benefits based on your ex-spouse's record.
However, if you remarried and that marriage ended in divorce, death, or annulment, you may regain eligibility. This part can vary, so be sure to check with the SSA.
Interestingly, it doesn't matter if your ex-spouse has remarried. Their new family situation does not affect your eligibility.
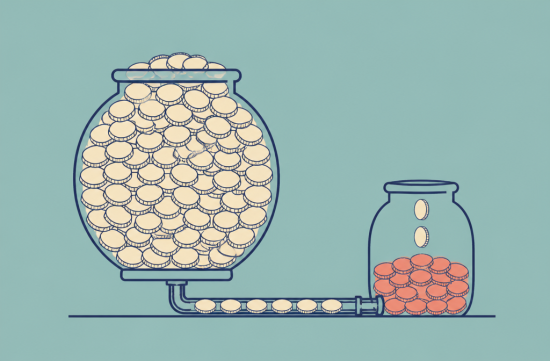
So, how much can you receive? The maximum is 50% of the primary insurance amount (PIA) that your ex-spouse would receive at their full retirement age.
Many people get confused here. It's not half of what your ex-spouse is currently receiving, but half of the amount based on their full retirement age.
And if you take it early, it gets reduced. According to SSA guidelines, if the full retirement age is 67 and you apply at 62, your ex-spouse's basic benefit could be reduced by up to 32.5%.
On the flip side, waiting past full retirement age doesn't increase it beyond 50%. It doesn't work like your own retirement benefits, which increase the longer you wait, so keep that in mind.
If you also have your own retirement benefits, you won't receive both amounts combined. You will receive the higher amount between your own benefits and the ex-spouse benefits.
This means if you've worked long enough to have a substantial pension, this system might not be very meaningful for you. Conversely, for those who have shorter work records due to childcare or other responsibilities, it can make a significant difference.
What if your ex-spouse hasn't applied for benefits yet? If it's been more than two years since the divorce and both of you are over 62, you can still receive benefits even if they haven't applied.
This information is also mentioned in a post on the SSA's official blog from October 27. It means you don't have to wait for your ex-spouse to apply and potentially lose out for years.
The most surprising part for me was that if I receive this benefit, it doesn't reduce the amount of the ex-spouse's benefit at all, nor does it affect their current spouse's share.
This holds true even if the ex-spouse has been married multiple times. If each of those marriages lasted over 10 years and met the conditions, they can all receive their respective benefits without reducing each other's amounts.
So, there's no need to contact or get permission from each other. I really appreciated that this is a right that can be quietly taken care of without any awkwardness.
If the ex-spouse has passed away, the situation changes. If the marriage lasted over 10 years, the divorced spouse can also receive survivor benefits, which can be applied for starting at age 60.
Another difference from spousal benefits is that if you remarry after age 60, you still maintain eligibility for survivor benefits. The regulations here are quite detailed, so it's safer to consult with someone.
You can apply online at ssa.gov or by calling 1-800-772-1213. If you don't know your ex-spouse's Social Security number, prepare their name, date of birth, and the dates of marriage and divorce as accurately as possible.
Make sure to have your marriage certificate and divorce decree ready. If you were married in Korea, you might need to have the documents translated, so it's good to allow some time for that.
For those living in Missouri, there's one more piece of good news. Starting in the 2024 tax year, Missouri will not impose state income tax on Social Security benefits.
Of course, federal taxes may still apply depending on your income level. Don't assume that all the money you receive will go straight into your pocket.
Since everyone has different work records and marriage histories, be sure to confirm the actual amounts and eligibility with the SSA or a professional. Even with a 10-year marriage, the numbers can vary widely.
If I were you, I would suggest making an SSA appointment right away if you qualify. If you let it slip by, no one will take care of that money for you.
If I run into those mothers at the market again, I'd like to gently remind them. Just because you've separated doesn't mean the pension benefits are off the table.
 AppleCopter
 walker1964


 American Politician Community |
 memorabilia |
 orvian89 |
 looksee 78 |
 vivavida |
 Flying Shooting Star |
 zeltrio |
 Lim Ario |
 norvexi |
 action blog 101 |
 athome blog |
 calvor |
 Haha and Bomi Blog |
 Lee Ton |
 viba viba |
 Olivia's Blog |
 208 Master |
 crumb |
 blanke |
 Burbank Lee |
 tervox95 |
 silverado |
 Grow Your Gut Bacteria Well |
 Kim You Shin |
 Squid Q |
 gelatonew |
 river9 |
 ttano |
 Eagle in America for Five Years |