
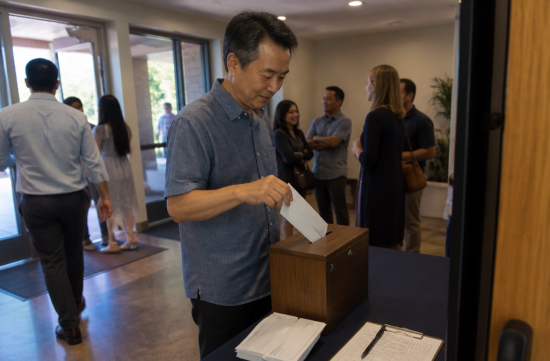
As I see the year-end special donation announcements in church bulletins, it's clear that the year is coming to a close. However, this year, there's something to consider before simply placing your donation in the envelope. This is because individuals who do not itemize deductions can now receive a deduction for their charitable contributions when filing taxes.
This is part of the so-called One Big Beautiful Bill Act, abbreviated as OBBBA, which was passed last summer. It will take effect starting with the 2026 tax year, meaning you can benefit from it when filing next spring.
Let me get straight to the point. Even those who take the standard deduction can receive a separate deduction for cash donations: individuals can deduct up to $1,000, and couples filing jointly can deduct up to $2,000.
This is good news because, until now, the donation deduction was essentially a benefit for those who itemized deductions. Since the standard deduction significantly increased after 2018, most households have opted out of itemizing, meaning that even if they donated, they received no tax benefits.
For reference, the standard deduction for 2026 will be $16,100 for individuals and $32,200 for couples filing jointly. Many homes do not exceed this threshold even when combining mortgage interest and property taxes.
The new deduction is structured to be added on top of the standard deduction. However, it does not lower your adjusted gross income (AGI); instead, it reduces your taxable income.
Some of you may remember a similar provision during the pandemic in 2020 and 2021. At that time, the amounts were much smaller and temporary. This time, it has been permanently included in the law, making it different.
Now, can any donation qualify? Not quite. This is where you need to pay attention before year-end.
First, only cash donations qualify. Checks, credit cards, and bank transfers count as cash. However, donations of items like clothing or furniture to Goodwill do not qualify for this deduction.
Second, the recipient must be a qualified charitable organization, such as a 501(c)(3). Organizations like churches, the Red Cross, and food banks typically qualify without issue.
Third, money placed into donor-advised funds, commonly referred to as DAFs, does not qualify. Contributions to some private foundations and supporting organizations also do not count.
Fourth, receipts are necessary. For donations of $250 or more made at one time, you must obtain written confirmation from the organization. This has always been a rule, but surprisingly, many people overlook it.
Timing is also important. This deduction applies starting with the 2026 tax year, so donations made at the end of last year do not qualify. Cash donations made by December 31 of this year will be the first eligible.
One more thing to note is that the limits are not indexed for inflation. This means that the amounts will remain at $1,000 and $2,000 regardless of the passing years.
Conversely, there is an unwelcome change for those who itemize deductions starting this year. Only the portion of donations that exceeds 0.5% of AGI will qualify for the deduction.
For example, if a household has an AGI of $200,000, the first $1,000 donated will not be deductible, but anything above that will be recognized. Honestly, this aspect is a bit disappointing. It feels like middle-class individuals who have consistently donated are unfairly losing out.
High-income earners in the 37% tax bracket will see the tax-saving effect of itemized deductions capped at around 35%. This means that not many people will fall into this category.
As a result, tax professionals are advising itemizers to concentrate their donations in 2025. While this may already be a thing of the past, the strategy of bundling several years of donations into one year remains useful.
For those approaching retirement age, we cannot overlook the discussion of Qualified Charitable Distributions (QCDs). If you are over 70 and a half, you can use eligible charitable distributions directly from your IRA to charities.
The QCD limit for 2026 is $111,000 per person. This amount does not count as income, so the 0.5% floor does not apply, and it is also recognized as part of the required minimum distribution (RMD).
California state taxes need to be considered separately. California often does not automatically follow federal tax law changes, and it is still unclear whether this deduction will be recognized on state returns.
Therefore, if you plan to include state taxes in your calculations, it's safest to check the guidance from the Franchise Tax Board. There have been many instances where people assumed that what was allowed federally would also apply at the state level, only to be disappointed.
In my opinion, this provision is genuinely a positive development. Rather than waiting for the government to do everything, it's better to encourage neighbors to help one another.
Small organizations like church donations, local food banks, and scholarship foundations have ultimately supported the community. If tax benefits can flow back to them, that's something to applaud.
If I were in your position, I would make cash donations within the $2,000 limit this year via bank transfer or check and keep the receipts organized in a folder.
If you are itemizing deductions, I would first calculate the 0.5% threshold and consider how to bundle donations over several years. If you are over 70 and a half, sending QCDs from your IRA is generally more advantageous.
However, the answer may vary depending on your income structure or retirement account situation, so if the amounts are significant, I recommend consulting a tax professional.
If you can do good while saving on taxes, that's truly a win-win situation. You can feel even better about placing your year-end donation envelope this year.
 Seoul2Austin


 victoria 68 |
 American Man in a Mask |
 kuku 100 |
 novent |
 Silent Sea |
 American Food Information & Calories |
 Tomato Health Club blog |
 Egg Steamed Pot |
 Helpful Life Stories |
 quanta7 |
 UNI Lover |
 zen zeng |
 oh my salami |
 wendra |
 coloradoman |
 business life |
 candytip |
 churrotop |
 swiftlane |
 allstar realty |
 mystery |
 dermoon |
 UCLA Captain |
 lattecu |
 dynamite |
 frostingline |