
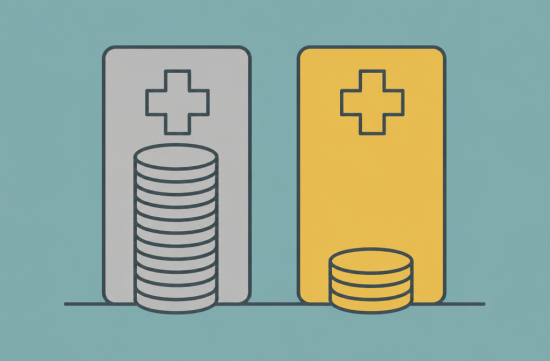
Last week, a friend of mine was discussing renewing their Obamacare plan and was puzzled. They mentioned that the Gold plan, which offers better benefits, was cheaper than the Silver plan. At first, it sounds like a calculation error, but this actually happens frequently in Texas.
Let's look at the numbers. According to data compiled by KFF for 2026, the average monthly premium for the cheapest Silver plan in Texas for a 40-year-old individual was $651.
In the same conditions, the average monthly premium for the cheapest Gold plan was $570. The Gold plan, which has a higher coverage ratio, was actually over $80 cheaper.
The national average is different. The cheapest Gold plan costs $615, while the benchmark Silver plan is $625, resulting in only a $10 difference. This indicates that the gap in Texas is particularly large.
Why does this reversal occur? The key is a pricing method called silver loading.
When low-income enrollees choose Silver plans, there is a cost-sharing reduction (CSR) program that lowers deductibles and copays. Originally, the federal government reimbursed insurers for these costs.
However, in October 2017, the federal government stopped these reimbursements. As a result, insurers began to add these costs to the premiums of Silver plans, which is known as silver loading.
Texas took it a step further. In 2021, the state legislature unanimously passed SB 1296, and starting in 2023, this method effectively became a state-level rule.
As a result, Silver premiums are priced much higher than their actual coverage value, while Gold premiums have increased relatively less. This is where the reversal phenomenon begins.
Here's an interesting point. Obamacare subsidies (premium tax credits) are calculated based on the second cheapest Silver plan, or benchmark Silver price.
If Silver prices are inflated, the amount of the subsidy also increases. This means that if you use that large subsidy for Gold or Bronze plans, the amount you pay out of pocket significantly decreases.
Therefore, for those receiving subsidies, the net premium for Gold plans can appear quite low. Even for those without subsidies, there are cases where the base price of Gold is lower than Silver, so there's no downside.
However, Gold is not always the right choice. If your income is below 250% of the federal poverty line, a Silver plan with CSR may have a much lower deductible.
Individuals in this income range should compare the annual out-of-pocket maximums for Gold and CSR Silver side by side. Choosing based solely on monthly premiums can lead to poor decisions.
Not all the cheapest Gold plans offer the same benefits. According to an analysis by Baylor College of Medicine, some Gold plans have been designed to raise deductibles in order to maintain premiums.
You should also check the network. Whether your usual Korean doctor or nearby hospital is included in the plan's network varies by plan.
If you are taking any medications, check the formulary as well. Before changing plans, it's best to consult with your doctor or pharmacist to ensure that your medications will continue to be covered.
This year, the situation has become more complicated. The enhanced subsidies that increased during COVID-19 are set to expire on December 31, 2025, and while the House passed an extension in January, there has been no confirmation that it has passed the Senate.
Perhaps as a result, the percentage of Texas enrollees choosing Bronze plans jumped from 18% in 2025 to 31% in 2026. This likely indicates that many have opted for plans with higher deductibles due to premium burdens.
Honestly, I find this aspect a bit disappointing. In Texas, where you could aim for Gold with the same subsidy, I believe many may have chosen Bronze due to a lack of understanding of the structure.
In Washington, there are discussions about having the federal government directly cover CSR costs again. The CBO estimates that this would lower benchmark premiums by 11%, but it would also increase the number of uninsured by 300,000.
While it may seem like a premium reduction on the surface, if benchmark Silver becomes cheaper, the subsidies will also decrease. It's worth noting that places like Texas, which benefit from Gold reversals, could be significantly affected.
The open enrollment for 2027 plans starts on November 1. To receive coverage starting January 1, you must enroll by December 15.
There are indications that the deadline itself may change depending on the outcome of lawsuits, so it's safest to check the announcements directly on HealthCare.gov.
My recommended order is simple. First, accurately input your expected income for next year, then display Gold and Silver plans side by side to compare monthly premiums and annual out-of-pocket maximums.
Finally, check the hospital network and medication list. If you leave it to automatic renewal, last year's plan will carry over, so be sure to compare directly this year.
If I were in your position, I would start by looking at Gold plans as long as my income exceeds the CSR threshold. There's no reason to pass up better coverage for the same amount of money.
 Student



 Tora Tora |
 neroyo |
 nivex85 |
 Old English |
 nixxon |
 U.S. Weather Bureau News |
 Things to know |
 Premium Gas Camp |
 Texas Real Estate Blog |
 action blog 101 |
 frostbite |
 330 Forever My Love |
 El Dorado |
 dralix58 |
 Gorama Round |
 Skydiving |
 dreamport |
 Yellow Snowman |
 Toaster Pizza Magic Show |
 velvetnom |
 Anytime Journey |
 Mrs. Duluth |
 jaxter |
 Atlanta Mama |
 Baguette Blog |
 Tan Sol |
 US Embassy |
 Korean Mom |
 My NYC |
 moo moo |