
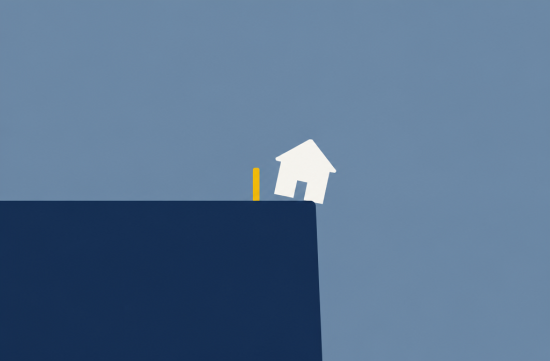
A while ago, a friend mentioned their parents were organizing their house and said, "New York has an inheritance tax that drops off like a cliff." At first, I thought it was just a metaphor, but upon looking it up, I found that the structure really is a cliff.
If you only consider the federal inheritance tax, most people think it doesn't apply to them. With the federal exemption set at $15 million per person in 2026, that's understandable. So, it's easy to think that inheritance tax is an issue only for the very wealthy.
However, New York State is a completely different story. There is a separate state inheritance tax, and the exemption threshold is much lower.
The basic exemption amount for New York residents who die on or after January 1, 2026, is $7.35 million. This is a slight increase from $7.16 million in 2025, adjusted for inflation.
Up to this point, we're just talking about the exemption limit. The problem arises at the next stage.
If the taxable estate in New York exceeds 105% of the exemption amount, the entire exemption benefit disappears. Based on 2026 figures, that threshold is $7,717,500.
The moment you exceed this threshold, tax applies not just to the amount over the exemption but to the entire estate. You can think of it as being taxed from the first dollar.
The range in between, that is, from 100% to 105% of the exemption, does not see the exemption disappear all at once; it gradually decreases. But this range is actually the most painful part.
According to an example published by the New York State Society of CPAs, the effective marginal tax rate can reach as high as 257% in this range. At first, I thought I had misread the numbers.
In simple terms, this means that a small amount exceeding the exemption threshold can lead to a much larger tax bill. That's why everyone refers to it as a cliff.
The tax rates themselves are progressive. The lowest bracket starts at 3.06%, and the highest rate of 16% applies to amounts over $10.1 million.
The $7.35 million figure might seem like a large number and feel distant. However, when you combine home values, retirement accounts, and life insurance payouts, it can add up quickly.
Especially, life insurance payouts can be a trap. If you have a policy in your name and you own it, the death benefit can be included in your estate. Sometimes, an old policy can significantly increase the total.
Another aspect that is easy to overlook is portability. While the federal government allows the surviving spouse to inherit the remaining exemption of the deceased spouse, New York does not recognize this.
So, if a couple simply passes all their assets to each other, the exemption may only be used once upon the death of the second spouse. This is why planning should be done on a couple basis.
Then you might think, why not just gift assets while alive? New York does not have a separate gift tax.
However, any taxable gifts made within three years of death are added back to the estate for calculation. This add-back rule was originally applicable only to those who died before January 1, 2026, but it has been extended to those who die before January 1, 2032.
Some old forms may still state the cutoff as 2026. Be sure to check the date on the latest guidance.
The deadline for filing New York State inheritance tax returns is nine months from the date of death. For survivors, time can pass quickly after handling funeral arrangements.
The obligation to file can also be confusing. If the total amount, including gifts that are part of the federal gross estate, exceeds the exemption amount, you may be required to file even if no tax is owed.
Opinions on this system vary. Those who believe high-net-worth individuals should bear a fair burden see no major issues, while others criticize it as a structure that drives retirees to move to Florida.
Personally, I find the design more disappointing than the tax itself. The way the tax burden spikes near the exemption threshold is hard to justify with data.
That said, it's not necessarily time to think about moving. Changing residency requires a legitimate basis for living elsewhere, and any real estate remaining in New York may still be subject to tax.
If I were in your shoes, I would start by organizing a list of assets numerically. This means writing down home values, 401(k) and IRA accounts, designated beneficiaries for insurance, and joint accounts on one sheet. You don't need any fancy tools; a simple spreadsheet will suffice.
If that total is near the exemption threshold, then it's truly the realm of experts. Depending on how you structure trusts, timing of gifts, and charitable donations, the outcomes can vary significantly.
Since applications differ based on individual circumstances, be sure to consult a New York State estate attorney or tax professional before making any decisions. Also, check the estate tax guidance on the New York State Department of Taxation and Finance website.
Knowing just a few numbers can change the conversation. Remember these four: $7.35 million, 105%, 3 years, 9 months.
If your parents' generation's wealth has grown more than you expected, now is the best time to bring up the conversation. It's much better to know the path ahead than to hit the brakes at the edge of a cliff.
 HappyChicken


 Burbank Lee |
 vibranto |

 sparkling |
 oh my salami |
 saffronroute |
 Dolly |
 Day by day |
 The Day the Sun Rises |
 Gold Bar |
 donutfield |
 Tennis City |
 sunny7 |
 Questions about firearms while living in America |
 Shoot Me |
 mochifox |
 zucchini |
 Anna Life |
 Exciting FM Radio |
 pet dog |
 toodin |
 rosed |
 DeArizona Blog |
 river9 |
 ollege Mom |
 Pronunciation Yo |
 nuvex11 |
 Living in Florida |
 axelon47 |
 lumbus |