
For those purchasing individual health insurance directly in Rhode Island, you may have received a letter from your insurance company in your mailbox recently. That letter indicates how much your premiums will increase next year.
This topic is not just about "another increase." Even though the same exchange is used in the same state, the rate of increase can vary significantly depending on which insurance company you are with.
First, let's clarify the basic structure. There are only two companies selling individual insurance on the Rhode Island health insurance exchange, HealthSource RI.
One is Blue Cross Blue Shield of Rhode Island, abbreviated as BCBSRI. The other is Neighborhood Health Plan of Rhode Island, commonly referred to as Neighborhood.
According to data released by the state's health insurance commissioner (OHIC) in June, as of the end of March 2026, there were 16,138 members enrolled in BCBSRI individual insurance. Neighborhood had over double that, with 34,555 members.
Combining both companies, there are 50,693 members in the individual market. While it's a small state, having only two options is something to consider.
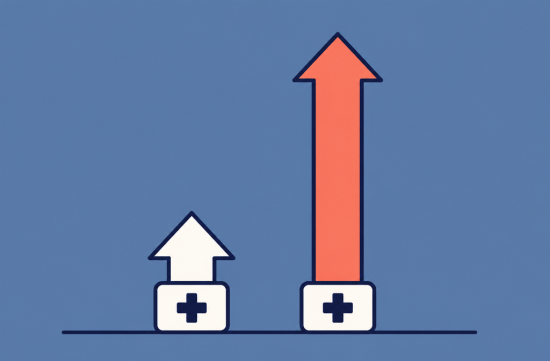
Now, let's look at the numbers. The average rate increase requested for 2027 was 9.8% for BCBSRI and 24.9% for Neighborhood.
This results in a difference of 2.5 times. The weighted average rate increase for the entire individual market, based on the number of enrollees, was 20.1%.
For reference, Neighborhood's request varies by plan, with increases ranging from 17.9% to 29.3%. This indicates that there was quite a bit of variation even within the same company.
Rhode Island opens a public administrative hearing if a rate increase request exceeds 10%. Therefore, Neighborhood underwent a hearing in July, while BCBSRI was not subject to a hearing as their request was below the threshold.
In the meantime, the state legislature created a new subsidy program called the Rhode Island Marketplace Affordability Program. Since this program will be implemented starting in 2027, Neighborhood adjusted their request to a 22.4% increase.
In August, Attorney General Peter Neronha submitted an opinion opposing the rate increase, citing that over 50,000 residents enrolled in individual insurance would be affected.
The final decision was made at the end of September. Insurance commissioner Cory King approved a lower increase of 15.8% for Neighborhood and 4.9% for BCBSRI compared to their requests.
Interestingly, the difference that was 2.5 times at the request stage widened to over three times after approval.
BCBSRI's initial request of 9.8% was cut in half. In contrast, Neighborhood's initial request of 24.9% was reduced by just over a third.
According to reports, the insurance commissioner reduced the amount requested by the insurance companies by over $86 million. This was explained as a reassessment of the assumptions regarding medical utilization and severity trends.
The response from the insurance companies has been understandably lukewarm. BCBSRI stated that the high cost of medical care was not reflected in the approved amounts, while Neighborhood claimed that it would face difficulties in investing in primary care.
For comparison, in 2026, an average increase of 21.0% was approved for the individual market. This means that there are quite a few enrollees facing double-digit increases for two consecutive years.
So what should we do? I like to organize things in order, so let's go through them one by one.
First, check which company your current insurance is with. Even if you live in the same neighborhood, the rate increase can be completely different depending on the company.
Second, remember that 15.8% and 4.9% are averages. Your actual bill may vary based on your plan, age, and subsidy amount.
Third, the open enrollment for 2027 starts on November 1. The deadline is somewhat ambiguous due to federal regulatory litigation, so it's safest to check directly on the HealthSource RI official website.
Fourth, if you're considering switching companies, don't just look at the premiums. Make sure to check with your doctor and pharmacist whether your current providers are in the network and if your medications are covered.
It's also important to check how the new state subsidy program will apply to your premiums. We will have to wait for the exchange to provide detailed criteria.
Personally, I believe the root cause of this situation lies in the market structure with only two options. Without competition, prices will inevitably be influenced by regulatory decisions.
While it's nice that the regulators are cutting costs, I don't think this method of having the government set the numbers every year can last long. Creating an environment where more insurance companies can enter is the long-term solution.
That said, we can't just sit back and wait for next year's premiums. If it were me, I would go to the exchange in early November and compare the plans from both companies side by side.
If you've received the notification letter, don't throw it away; take a moment to read it carefully. Investing just a few minutes can significantly change your insurance premiums for the year.
 goldenriverfox1952



 Churros Train Conductor |
 Tora Tora |
 neroyo |
 nivex85 |
 Old English |
 Rhode Island Good People |
 Jazz Queen |
 Sunny Sunday |
 USALATU BLOG |
 Roman Pan |
 Sunshine Blog |
 Minnesota Small Business |
 Strawberry Pancake Warrior |
 amolayo |
 korvon |
 Que Buena |
 virexo |
 silverpath |
 Komet Park |
 reliable |
 vexo90 |
 As Always Today |
 veltar87 |
 United States National Administrative Organization Stories |
 springwaltz |
 dense |
 Tiger Milk Foam Research Institute |
 Oreore Mushroom |