
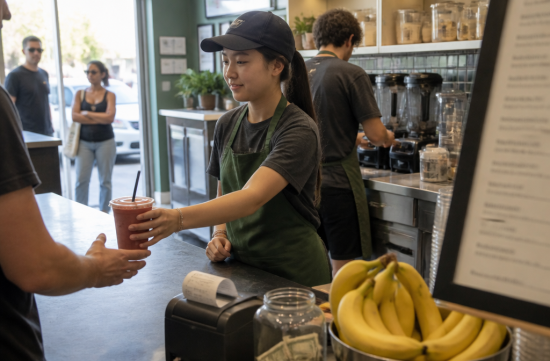
Last week in the evening, an old friend called me. Their child is starting a summer job at a local smoothie shop and was excited to receive their first W-2.
Then they asked me. Someone mentioned that it would be good to open a Roth IRA in the child's name, and they wanted to know if that was really possible.
After hanging up, I stared out the window for a while. The thought that a sixteen-year-old's first paycheck could become retirement savings decades later was strangely touching.
To get straight to the point, yes. If a minor child has earned income, parents can open a custodial Roth IRA for them.
The key condition is simple: earned income. There is no age limit, but the child must have earned money that year.
Receiving a W-2 from a job certainly qualifies. Income from babysitting or mowing lawns is also recognized, but you must keep a record of the dates and amounts.
On the other hand, allowances, gifts, or stock dividends do not count as earned income. Confusing these can lead to issues with excess contributions.
If the income exceeds $400 in net earnings, there may be a self-employment tax reporting obligation. Even if the income is low enough not to require tax filing, keep the W-2 and pay stubs for several years.
The IRA contribution limit for 2026 is $7,500, up from $7,000 last year.
However, the child can only contribute up to the lesser of this limit or their earned income for the year. If they earned $2,000, then $2,000 is the maximum they can contribute.
With California's minimum wage at $16.90 per hour this year, the math is straightforward. If they worked 100 hours over the summer, that would be $1,690 before taxes, which is the maximum they can contribute this year.
Many people overlook an important point here. The money contributed does not necessarily have to come from the child's account.
The child can spend their earnings, and the parents can contribute the same amount as a gift. The only requirement is based on the child's total earned income.
I suggested this approach to my friend. I recommended a family match where if the child saves $1, the parents contribute an additional $1.
The appeal of a Roth IRA lies in its tax structure. You contribute money that has already been taxed, and if certain conditions are met, you can withdraw the earnings tax-free.
Teens typically have low income, so they pay very little or no taxes at all. Therefore, contributions made during this time are particularly efficient.
It can also alleviate concerns about college tuition. The FAFSA does not count retirement account balances as assets, making it more advantageous than keeping the same money in the child's name.
Additionally, the principal, or contribution, can be withdrawn at any time without taxes or penalties. This serves as a safety net for urgent expenses like college tuition or a first car.
The earnings portion is different. You must meet conditions such as waiting five years from the first contribution and being at least 59 and a half years old to withdraw tax-free.
There is an exception for first-time home purchases, allowing you to withdraw up to $10,000 in earnings without a 10% penalty. If you meet the five-year requirement, you are also exempt from taxes.
Contributions for this year can be made until the tax filing deadline of April 15, 2027. Since it's October now, there's no rush, but it's a good idea to open the account before the end of the year for peace of mind.
Accounts can be opened online at most brokerage firms, with the parents listed as custodians. When the child becomes an adult, control of the account will transfer to them.
The age at which this transfer occurs can vary by state law and financial institution, typically at 18 or 21. Be sure to check before opening the account.
Honestly, there are some uncomfortable aspects. It's disheartening to see brokerage ads presenting a child's retirement account as if it were a report card for the parents.
Not every family has the luxury of saving, and many rely on part-time earnings to help with living expenses. For those families, retirement savings may seem like a luxury.
Another concern is that when the child turns eighteen and gains control, they might withdraw all the funds. This can happen if you only deposit money without having a conversation.
So, I would prioritize discussion over the amount. I would suggest looking at a compound interest graph together at the dinner table and letting the child choose which fund to invest in.
Searching for index funds that consider environmental or social values can also be a valuable learning experience. Understanding where your money flows can have a lasting impact.
A few days later, my friend called again. Their child decided to start with a $300 contribution, and they matched that amount.
It's not a large sum. Still, I believe that the experience of making that first choice with the $300 may become a more valuable asset than the account balance itself.
 OTEscape


 Way to easy |
 Magic Cabbage School of Martial Arts |
 Vacation on Hawaii |
 morvex37 |
 Ari Songhan American Immigration Life |
 US Embassy |
 K-POP TV News |
 Old English |
 ollege Mom |
 Pronunciation Yo |
 nuvex11 |
 Living in Florida |
 axelon47 |
 lumbus |
 Texas Migration Story |
 Scade Studio |
 love ya |
 biscuit90 |
 chicpo |
 Helpful Life Stories |
 Kitchen Ideas |
 Diana Blues |
 Agenda Center |
 Community Cross |
 journey |
 heeve |
 leman |