
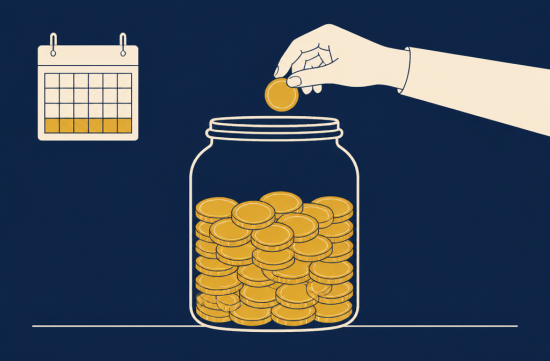
Last week, while looking at my paycheck, I paused at the accumulated amount in my 401(k). I had promised myself at the beginning of the year to max it out, but seeing the number, I realized I was far from it.
Coincidentally, a coworker showed me an article stating that the limit will increase again next year. So, this weekend, instead of focusing on skincare ingredient lists, I found myself fixated on my 401(k) numbers.
First, let's clarify the current limits. For 2026, the employee contribution limit for 401(k) plans is $24,500, which is an increase of $1,000 from $23,500 in 2025.
Those aged 50 and over can contribute an additional $8,000 as a catch-up contribution, bringing the total to $32,500.
For those aged 60 to 63, a special catch-up applies, allowing contributions of up to $11,250 instead of $8,000. It can be confusing because you don't receive both; it's a switch to the higher amount.
The total annual limit, including company matching, is projected to be $72,000 in 2026. This number is different from the employee contribution limit, so don't mix them up.
So, what about 2027? There hasn't been an official announcement from the IRS yet, and what we have now are just projections.
According to a forecast from the consulting firm Milliman, which reflects inflation data up to August, the employee contribution limit is likely to rise to $25,500, an increase of $1,000. The catch-up contribution for those over 50 is also expected to rise to $8,500.
However, there are conditions. If the consumer price index for September shows only a slight increase, the limit may remain at $25,000, and the catch-up could stay at $8,000.
The total limit, including company matching, is expected to be $75,000. The IRS typically announces the limits for the following year between late October and November after the September inflation data is released, so we'll have confirmed numbers soon.
Honestly, I'm more upset about not maxing out this year than I am about the limit increasing. Once next year's numbers are announced, I can adjust, but there's no way to make up for the money I couldn't contribute this year.
So, let's go over what you should definitely do before year-end. The first step is to check your accumulated contributions on your paycheck.
Since 401(k) contributions are deducted from your paycheck, only the amount contributed up to your last paycheck of the year counts for this year. I didn't realize this at first, as it's different from an IRA, where you can contribute until April tax filing.
The second step is to divide the remaining number of pay periods by the limit minus your accumulated amount. This will show you how much more you need to contribute per paycheck to reach the limit.
Each company may take one or two pay cycles to reflect changes in contribution rates. So, if you plan to make changes, it's best to do so by October.
The third step is to understand your company's matching policy. If your company matches contributions every month, you might miss out on matching for the remaining months if you hit the limit too early.
Be sure to check your plan documents or ask your HR department if there's a true-up policy at year-end. There's nothing worse than missing out on free money.
The fourth step is for those who changed jobs this year. The employee contribution limit is based on individuals, not companies, so you cannot exceed $24,500 by combining contributions from two different 401(k) plans.
Since your new company won't know how much you contributed at your previous job, you need to keep track. If you exceed the limit, you must withdraw the excess by April 15 of the following year to avoid double taxation.
The fifth step involves changes for high-income employees over 50. Starting in 2026, if your FICA wages from the previous year exceed $150,000, you must make catch-up contributions as Roth contributions only.
If your company plan doesn't offer a Roth option, those individuals may not be able to make catch-up contributions at all. This threshold amount is also adjusted annually based on inflation, so it's good to check next year's numbers as well.
Finally, set your contributions for next year in advance. If you contribute as a percentage rather than a fixed amount, the limit increase won't automatically adjust your contributions, so you'll need to recalculate your percentage once the announcement is made.
Many companies are currently in open enrollment, making it a good time to review your benefits alongside insurance. I plan to sort out my HSA and 401(k) at the same time.
In fact, I tend to scrutinize every ingredient when buying cosmetics, yet I left my retirement funds untouched at the percentage I set at the beginning of the year. This experience has made me realize that, like skincare, managing money requires consistent attention to see results.
Of course, I'm not saying you must max out your contributions. If you don't have an emergency fund or have high-interest credit card debt, those should come first.
But do make sure to take advantage of any matching contributions. Personally, I would contribute at least up to the match limit and, if possible, direct any year-end bonuses into my 401(k).
Once the official 2027 limits are announced, I'll provide a summary with the confirmed numbers. In the meantime, take just 10 minutes this weekend to check your paycheck.
 SodaQueenz

 My NYC |
 coloradoman |
 Living Economy Information Blog |
 Tomato Health Club blog |
 Banana Style Life |
 Hoorah Ooorah |

 Iowa Egen Aunt |

 Iowa School News |
 Tonky |
 viroma |
 cookie |
 Live and that's it |
 Alright Twain |
 eatontown blog |
 HAWAII Korean Church News |
 Amore |
 linex |
 Balancework |
 laro90 |
 MEDBIO American Doctor Blog |
 SWAT TEAM BLK |
 DREAM BIG |
 frostbite |
 330 Forever My Love |
 El Dorado |
 dralix58 |
 Gorama Round |
 Skydiving |