
The housing market in Salt Lake City has shown a steady upward trend in recent years. According to Redfin, as of May 2026, the median sale price over the last three months is $585,000, which is a 3.5% increase from a year ago. For single-family homes, the median price has risen to $685,000 as of June (Redfin). This raises the first question: how much should you prepare for a down payment?
Based on the $585,000 figure, a 3.5% down payment would be $20,475, 5% would be $29,250, 10% would be $58,500, and 20% would be $117,000. So, is it always advantageous to start with a lower percentage? Not necessarily. If the down payment is less than 20%, PMI (Private Mortgage Insurance) will be required, increasing monthly costs, while amounts over 20% are exempt (NerdWallet). The right choice between an initial lump sum and monthly burdens varies by household.
How much does your credit score affect this? As of July 2026, the 30-year fixed mortgage rates are 6.59% for credit scores above 780, 6.66% for the 760s, 6.75% for the 740s, and 6.91% for the 700s (themortgagereports.com). Even with the same loan amount, a difference in credit score can change your monthly payment, so it's wise to manage your score a few months before applying.
In Utah, there is a first-time homebuyer assistance program called FirstHome Loan from the Utah Housing Corporation (UHC). In addition to a lower 30-year fixed rate than the market, you can receive a second mortgage with no interest for up to 6% of the purchase price to assist with the down payment (UHC, as of 2026). Additionally, there are separate programs funded by the state legislature that can provide up to $20,000 for purchasing new homes (under $450,000), but since the budget is limited, it's advisable to check with a loan officer about current availability.
When preparing for a down payment, you should also account for closing costs. Typically, closing costs range from 2% to 5% of the loan amount, and there are cases where UHC funds are redirected to cover closing costs instead of the down payment. Addressing this during the pre-approval stage can help reduce the need to adjust your budget later.
What is a safe DTI (Debt-to-Income) ratio? For Qualified Mortgages, a back-end DTI of 43% or lower is recommended, while conventional loans generally range between 36% and 45% (Consumer Financial Protection Bureau). Avoid purchasing a new car or opening new credit cards just before applying, and have your income documentation organized and recent to streamline the approval process. Many lenders also consider whether you have enough reserves to cover several months of principal and interest after closing, so it's a good idea to check your bank balance beforehand.
What about property taxes? The effective tax rate in Utah is 0.53% (propertytaxrates.org, as of 2026). For a $585,000 home, that amounts to about $3,100 annually. This effective rate already reflects a 45% reduction benefit applied to owner-occupied homes, so if you're moving from another state, you may find the actual tax rate feels lower than where you previously lived. Since rates can vary by county, it's wise to verify the Salt Lake County rate before purchasing.
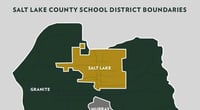
Korean families often consider school district ratings as well. While resources like GreatSchools or state education department ratings can be helpful, school district boundaries can change annually, so it's best to verify the actual school assigned to the address you intend to purchase. If you're relocating from another state, it's safer to compare insurance rates and overall living costs rather than relying solely on the standards from your previous state.
Ultimately, obtaining pre-approval to confirm your budget range and weighing the down payment percentage against monthly burdens is the most realistic approach. This information is not investment or legal advice, and it's recommended to consult with a loan officer and real estate expert before finalizing any contracts.
 Trendya
 SunnyField74



 moo moo |

 ultron78 |

 garlic bread |

 Sugar Cream Door Bulletproof Noodles |

 urbanmint |
 Tan Sol |
 AliAluAlo Blog |
 morvex37 |
 KGOMIO Blog |
 The Gelaton |
 Twist Kim |
 berlon93 |
 Physical Laws and Science |
 good thinking |
 Solo Yolo |
 Mr Oh |
 laro90 |
 San Diego TOP Idol |
 Round and Round Children's Song Kingdom |
 American Golf Course Travelogue |
 MEDBIO American Doctor Blog |
 Hot Seat Driver |
 bryvexi |
 koala organic farm |
 riverstone |
 My Antonio |
 California Information News |
 chilli chilli |
 Moon Su San |