
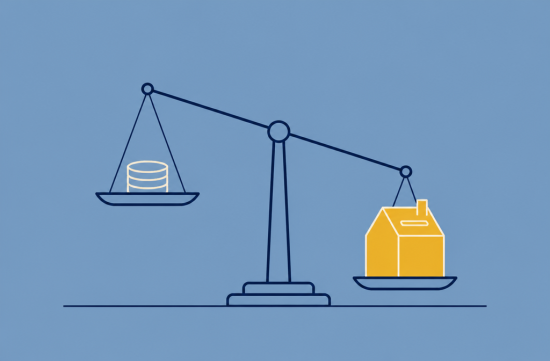
The home insurance renewal notice has arrived. I had a rough idea before opening the envelope, but seeing the numbers confirmed it: the rates have indeed gone up.
In situations like this, the first thing that comes to mind is the deductible. Everyone knows that raising your deductible lowers your premium. The question is, by how much, and is it really worth it?
First, let's look at the background. According to Insurify, the average annual home insurance premium in the U.S. for 2025 was $2,948, which is a 12% increase from the previous year.
In California, the situation is more complicated due to wildfire risks. Many homeowners are being denied renewals, so simply receiving a renewal notice is a fortunate situation.
For reference, California insurers must notify homeowners in writing at least 75 days before the expiration date if they intend to deny renewal. If you receive a renewal notice instead of a denial, it means your contract will continue.
Now, let's get to the main point. How much can you actually save by raising your deductible?
The Insurance Information Institute (III) states that raising your deductible from $500 to $1,000 could reduce your premium by up to 25%. The key word here is "up to." There is a caveat that results can vary significantly based on the insurer, location, and claims history.
The actual average savings are much lower. An analysis by InsuranceQuotes.com in 2016 found that when raising the deductible from $500 to $1,000, the average savings was 7%.
In the same analysis, raising the deductible to $2,000 resulted in about a 16% reduction. There are also significant state-by-state variations, with some states seeing savings of less than 3%.
Honestly, when I first saw these numbers, I was a bit disappointed. If you expect a 25% reduction and get quotes, most will stop at single-digit percentages.
So, I calculate based on the break-even point rather than percentages. In engineering terms, this means converting risk into monetary value.
Let's consider a hypothetical example. Suppose a home has an annual premium of $2,000 and raises its deductible from $1,000 to $2,000, saving $150 per year.
The additional risk taken on is $1,000. Dividing $1,000 by $150 gives approximately 6.7 years.
This means you would need to go nearly 7 years without making a claim to break even. If you file a claim even once during that time, the calculations change dramatically. Data shows this is a probability game.
On the other hand, if the savings were $300 per year, you would break even in just over 3 years. In such cases, there is sufficient justification for raising the deductible.
Ultimately, the answer depends on your insurance quotes. Ask your agent to provide quotes for deductibles of $1,000, $2,500, and $5,000. Laying the numbers side by side will make it easier to decide.
One important thing to check is whether the deductible on the notice is a fixed amount or a percentage.
A percentage deductible is based on the dwelling coverage. If the coverage amount is $400,000 and the deductible is 2%, then the out-of-pocket cost would be $8,000.
The number "2%" may seem small and easy to overlook. However, when converted to actual dollars, the situation changes completely.
Additionally, standard home insurance does not cover earthquakes. Earthquake coverage is a separate policy, and the deductible structure should be considered separately. It's not surprising if there's no earthquake item on the notice.
If you raise your deductible, it's advisable to set aside an emergency fund accordingly. If you can't readily access $2,500 on the day your roof leaks, that's not saving; it's just deferring risk.
Besides the deductible, there are other levers you can use. The California Department of Insurance (CDI) advises that bundling home and auto insurance can lead to discounts of 5-20% depending on the insurer.
The Homeowner's Premium Survey on the CDI website allows you to compare premiums by insurer. I recommend checking it out while you have your renewal notice in hand.
If you've taken steps to mitigate wildfire risks, make sure to mention that as well. California insurers are required to offer discounts for wildfire risk reduction measures.
It's also important not to file claims for minor damages. Your claims history can affect your premium at the next renewal and can follow you if you switch insurers.
When you think about it, people who raise their deductibles are typically those who don't file small claims. For such individuals, a higher deductible becomes a reasonable choice.
If you have questions, you can contact the CDI consumer hotline at 800-927-4357.
My conclusion is clear. If you have a healthy emergency fund and haven't filed a claim in over 5 years, I would raise my deductible to around $2,500 and put the savings into my emergency fund.
Insurance is not a product for covering small losses; it's designed to prevent catastrophic losses. I take responsibility for the small stuff and leave the big stuff to insurance. That's the most practical structure I see.
 SaveToBroke


 SKy Face |
 gleeful |
 forevergee |
 mortrix |
 cherrydino |
 United States National Administrative Organization Stories |
 Forever Tiger Teacher |
 cathywhite |
 U.S. Weather Bureau News |
 vegas mom |
 Olivia's Blog |
 heartbreaker |
 Giant Squid and Sweet Potato Soup |
 Valley Hong |
 The Gelaton |
 Twist Kim |
 berlon93 |
 Physical Laws and Science |
 good thinking |
 Solo Yolo |
 Mr Oh |
 laro90 |
 San Diego TOP Idol |
 Round and Round Children's Song Kingdom |
 American Golf Course Travelogue |
 MEDBIO American Doctor Blog |
 Hot Seat Driver |
 bryvexi |