
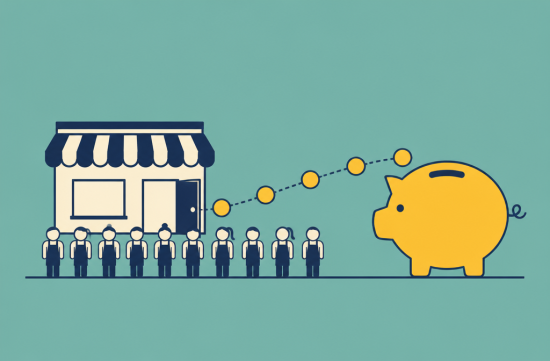
Last week, while chatting with the owner of my favorite nail salon, I was surprised to hear that she received a letter from the state government requiring her to register for a retirement plan, even though she has over a dozen employees.
The owner said, "Isn't that only for businesses with more than 25 employees?" I thought the same. So, I went home and looked it up right away.
To cut to the chase, that requirement has changed. It's now applicable starting from 10 employees instead of 25.
New Jersey has a state retirement savings program called RetireReady NJ. Its original name was the New Jersey Secure Choice Savings Program, and it started in June 2024.
The initial rules were as follows: businesses operating in New Jersey for over two years, with more than 25 employees in the previous year, and without a retirement plan like a 401(k), were required to register.
The registration deadlines were also staggered by size. Businesses with 40 or more employees had a deadline of September 15, 2024, while those with 25 to 39 employees had until November 15, 2024.
However, on January 20, 2026, Governor Cheryl signed Bill A5358, which lowered the mandatory threshold to businesses with 10 or more employees.
The state treasury announced in a July press release that they would begin informing employers and employees about this expansion starting in early September. As of the time I checked, the exact registration deadline for companies with 10 to 24 employees had not been officially announced.
So, if you received a letter like the nail salon owner, don't ignore it. Be sure to check the deadline directly from the letter and the official website.
Also, keep in mind that part-time employees count towards the total, which many people tend to overlook. Most explanations include weekend workers in the count.
So, what does the owner need to do? It's simpler than you might think.
They need to register the company, submit the employee list, and deduct contributions from payroll. The state government handles the investment management.
Here's some good news: employers don't pay any fees. They are not liable for the fiduciary responsibility regarding the investment results of employees; that role is handled by the state government committee.
However, employers are not allowed to match contributions with company funds under this program. If they want to enhance employee benefits through matching, they should look into other plans like a 401(k) or SIMPLE IRA.
From the employees' perspective, how does it work? The basic contribution rate is 3% of their after-tax salary.
This rate automatically increases by 1% each January, up to a maximum of 10%. While it may seem small at first, it adds up significantly over the years.
The accounts are primarily Roth IRAs, but employees can switch to Traditional IRAs if they prefer. For the first 30 days, funds are placed in a principal-protected product, after which they are moved to a retirement fund tailored to their birth year.
Employees can opt out at any time. If they opt out within 30 days of being informed, no deductions will start, and they can rejoin later.
Eligible employees must be at least 18 years old and receive taxable wages from a New Jersey employer.
There are some costs for employees as well. An annual account fee of $26 is deducted quarterly at $6.50, and there are separate asset-based fees.
From the owner's perspective, the tasks boil down to three things: registration, managing the employee list, and sending payroll deductions.
When new employees come on board, they just need to add them to the list.
Now, the most pressing question: what happens if they don't comply?
According to the law, the first year incurs a written warning, and in the second year, there's a $100 fine. In the third and fourth years, it's $250 per employee who has neither enrolled nor opted out, and from the fifth year onward, it jumps to $500 per employee.
What's even scarier is if they withhold money from employee wages and fail to send it, the first violation incurs a $2,500 fine, and subsequent violations are $5,000.
If a business with 15 employees neglects this for a few years, the numbers can escalate quickly. I found myself gasping as I calculated the potential fines.
If they already have plans like a 401(k), SEP, or SIMPLE IRA, they are exempt. However, they still need to report the exemption to the program.
Honestly, for business owners, it probably feels like just one more piece of paperwork. I completely understand the frustration of being busy with business and having to deal with more requirements.
Still, from the perspective of freelancers like me, it's an enviable system. Just having the company open the door to retirement accounts changes the starting line for employees.
If I were the owner, I would first check if our business is eligible at retireready.nj.gov. Then, if the employee count is unclear, I would consult an accountant and make sure to complete the registration or exemption reporting without delay.
Investing 10 minutes today is a much better choice than scrambling after receiving a fine letter. The nail salon owner plans to register this week!
 BrightTrail85

 loran |
 DeArizona Blog |
 Swift Falcon |
 Tonky |
 My NYC |
 velvetnom |
 Winter bear |
 US 210 Kim Sangsa |

 Always Flowing, That's All |
 eatontown blog |
 Well Done Sir |
 dance dance |
 sweetpepe |
 vegas mom |
 Olivia's Blog |
 cathywhite |
 heartbreaker |
 Giant Squid and Sweet Potato Soup |
 Valley Hong |
 The Gelaton |
 Twist Kim |
 berlon93 |
 Physical Laws and Science |
 good thinking |
 Solo Yolo |
 Mr Oh |
 laro90 |
 San Diego TOP Idol |
 Round and Round Children's Song Kingdom |
 American Golf Course Travelogue |